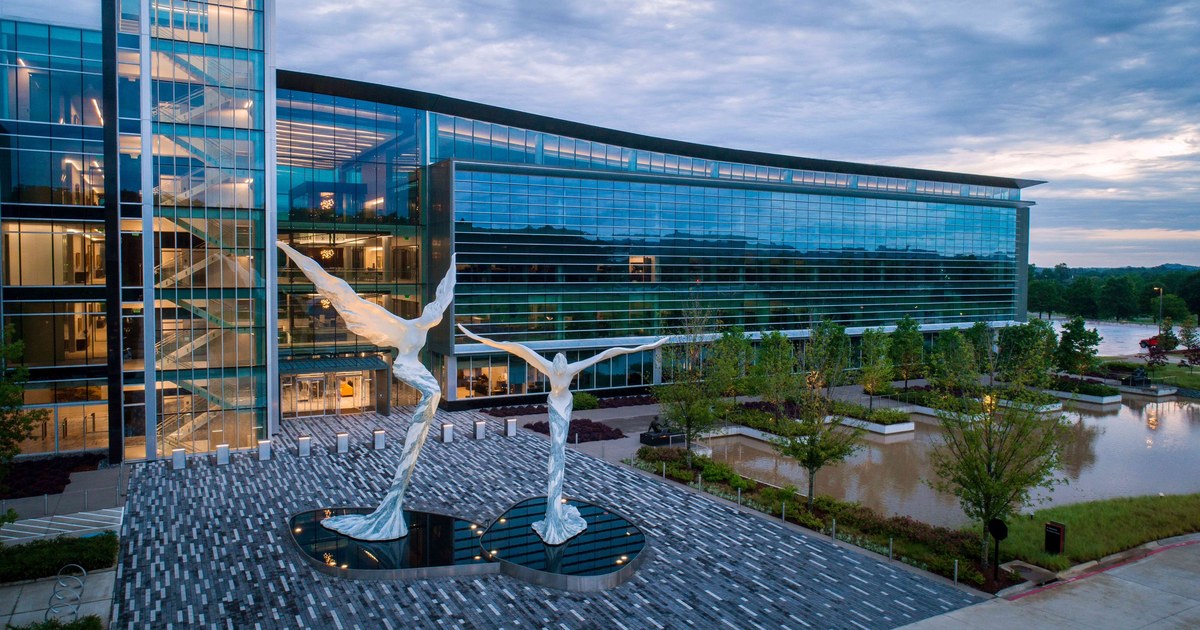
Little Rock-based Bank OZK earned $164.3 million for common stockholders in the third quarter, down 9 percent from the same quarter last year but slightly ahead of the second quarter, the bank reported after the market closed Tuesday.
Diluted earnings came to $1.50 a share, down from $1.59 a year ago and up from $1.49 in the second quarter. That beat the $1.45 average estimate of seven analysts surveyed by Zacks Investment Research, The Associated Press reported.
The bank set records for total assets at $43.2 billion, loans at $34.1 billion and deposits at $34.8 billion as of Sept. 30.
“We are pleased to report our solid financial results for the quarter,” Chairman and CEO George Gleason said in the release. “We continued to make significant progress on numerous strategic initiatives. We believe we are well-positioned for the future.”
For the first nine months of the year, net income available to common stockholders was $487 million, down 7.7 percent from $527.4 million in the same period of 2025.
Article continues below
▼ Continue reading
The numbers
Net interest income, the difference between what the bank earns on loans and investments and what it pays on deposits, was $403 million, down 2.6 percent from a record third quarter last year but up 2.8 percent from the second quarter, according to the bank’s management comments and financial supplement filed with federal regulators.
Its net interest margin was 4.24 percent, down from 4.35 percent a year ago and unchanged from the second quarter. The bank said its margin topped the industry average by 0.92 percentage points in the second quarter, the latest period with comparable data.
The bank’s efficiency ratio was 39.9 percent, meaning it spent about 40 cents to bring in each dollar of revenue. Its annualized return on average assets was 1.55 percent, down from 1.74 percent a year ago.
Non-interest income, mostly fees, was $36.3 million, about flat with a year ago. Non-interest expense rose 11.6 percent to $177.8 million, driven partly by costs tied to foreclosed and nonperforming properties. Insurance, taxes and other costs on those properties climbed to $9.8 million from $1.3 million a year earlier, and write-downs on foreclosed assets rose to $4.3 million from about $500,000.
Shifting away from big real estate loans
The bank has long been known for its Real Estate Specialties Group, which makes large construction loans on projects such as apartments, condos and office buildings in major cities across the country. That group’s share of the bank’s loans fell to 45.2 percent at the end of September, down from 47.6 percent three months earlier and from an all-time high of 70 percent.
Meanwhile, the bank’s Corporate and Institutional Banking unit, which lends to businesses, grew its loans by $1.39 billion during the quarter to $8.63 billion, or 25.3 percent of the portfolio, up from 13.6 percent a year earlier. The unit has grown from 18 employees at the end of 2023 to 133. The bank said it expects that unit’s loans to pass the real estate group’s sometime in 2027.
Repayments and other activity cut the real estate group’s balances by $1.65 billion in the quarter and $9.16 billion over the past year, as projects behind the group’s record 2022 lending are sold or refinanced. The bank said about $690 million came back in the first 19 days of October alone and that fourth-quarter repayments could be at or near a record.
Because of those payoffs, the bank expects loan growth of 3 percent to 5 percent for all of 2026. It expects growth to pick up to 10 percent to 12 percent in 2027.
Problem loans
The bank set aside $47.8 million for credit losses in the quarter and charged off $44.5 million in loans, net of recoveries, an annualized rate of 0.53 percent of loans. Its allowance for credit losses stood at $621.1 million.
Nonperforming loans dropped to $89 million, or 0.26 percent of loans, from $300 million at the end of June. The bank said a nonaccrual loan on a hotel in Wauwatosa, Wis., was paid off when the property sold, a loan on a Seattle office building was recapitalized by its sponsor and a new partner, and a Boston life science project moved into foreclosure.
Foreclosed assets, which now include the Boston property, rose to $420 million from $293 million, so total nonperforming assets were $510 million, or 1.18 percent of total assets.
Bank management wrote that the commercial real estate cycle “has proven to be an unusually challenging and prolonged period for some of our CRE customers,” but said it is seeing signs of improvement, including more financing available for projects. It said uncertainty remains for some office and life science properties and that net charge-offs could stay elevated as “a small number” of developers may stop supporting their projects in 2026 and 2027.
Rates, buybacks and dividends
Loan yields rose slightly in the quarter, which the bank attributed in part to “the initial impact of the recent 25-bps increase in the Fed funds rate.” It expects deposit costs to rise more in the fourth quarter and its margin to dip to somewhat below the 4.20 percent it posted in the first quarter. It also said $350 million in subordinated notes issued in 2021 switched from a fixed 2.75 percent rate to a floating rate on Oct. 1 and will cost 6.14 percent in the fourth quarter.
Book value per common share fell 88 cents in the quarter to $53.59, which the bank blamed on paper losses in its bond portfolio “resulting from the largest bond market sell-off in decades.” Book value is still up $2.50 over the past year.
The bank bought back about 650,000 of its own shares for $31.4 million in the quarter, at an average of $48.21, and another 520,000 shares for $23.8 million in the first 19 days of October, at an average of $45.85. Those were the first purchases under a $200 million buyback program that took effect July 1.
On Oct. 1, the bank raised its quarterly common dividend by a penny to 49 cents a share, paid Tuesday. The bank said it has raised the dividend in each of the last 65 quarters.
The bank, established in 1903, has 268 offices in nine states, including 256 retail branches in Arkansas, Georgia, Florida, Texas, North Carolina and Tennessee. It had 3,257 full-time-equivalent employees at the end of September, down 94 over the past two quarters after what the bank called a fine-tuning of staffing plans.
Executives will take questions from analysts on a conference call at 7:30 a.m. Wednesday, available by webcast on the bank’s investor relations site.
Get the biggest Arkansas stories in your inbox
Breaking news, arrests and court updates from across the state. Free.
Confirmation email required. Powered by Mailchimp.
Comments
No comments yet.
Members only
Comments are for members
Members can comment on every story and reply to each other. Join at any level, from $5 a month.
Become a member Already a member? Sign in